A Dubai Transition Consultants guide · Version 1.0
Leaving the UK cleanly
The departure year, explained
Download the PDFStart here
The flight changes nothing.
UK tax stops when your UK tax residence ends. HMRC settles that with a test, one tax year at a time.
The test
Three questions, asked in this order
The Statutory Residence Test stops at the first one that gives an answer.
- It is run again for every tax year, 6 April to 5 April.
- A day is a UK day if you are there at midnight.
- A UAE visa or tax certificate plays no part in it.
The ties
The more ties you keep, the fewer days you get
| Tie | What counts | What people forget |
|---|---|---|
| Family | A spouse, partner or child under 18 living in the UK. | Move ahead of the family and you hold it from day one. |
| Accommodation | A UK home that stays available to you. | The house kept “just in case”. A relative’s spare room can count. |
| Work | Enough days of real work done in the UK. | Client calls and laptop days on a visit are work. |
| 90-day | More than 90 UK days in either of the last two tax years. | One heavy year follows you for the next two. |
| Country | More midnights in the UK than in any other single country. | Split the year across several countries and the UK can still come top. |
The first year away sets your ties for the two after it.
The departure year
Leaving mid-year does not split the year
Split-year treatment does, and only when your move meets one of HMRC’s cases.
Starting full-time work overseas
The usual case for a UAE job. Hours, UK days and UK work days are all tested.
Ceasing to have a UK home
You give up the UK home and settle abroad.
Joining a partner working overseas
For a spouse or partner who moves with them.
Days after you leave
There is no safe number
Ninety is the figure people quote. Yours comes from your ties and your departure year.
Go one day over, and the whole tax year can be UK resident.
Keeping the count, and the record
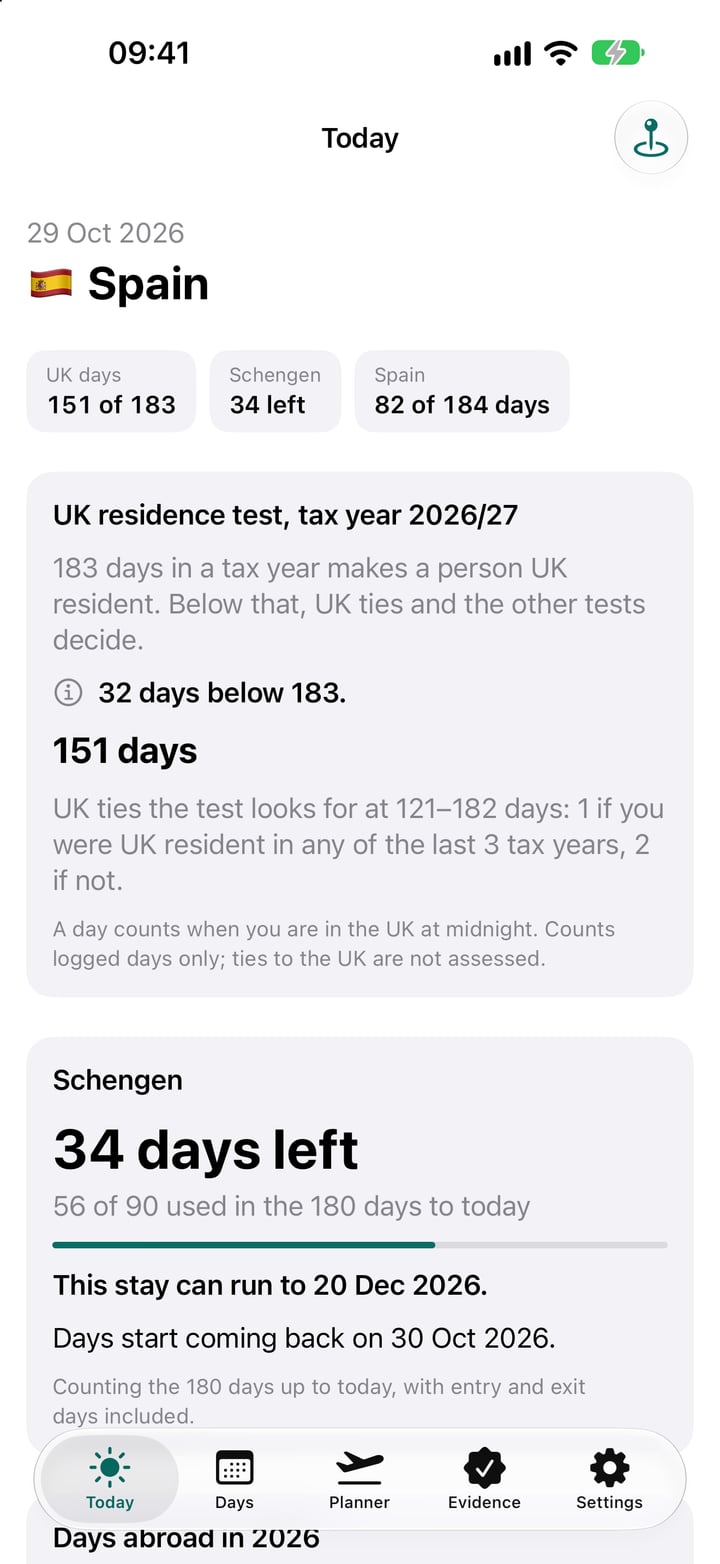
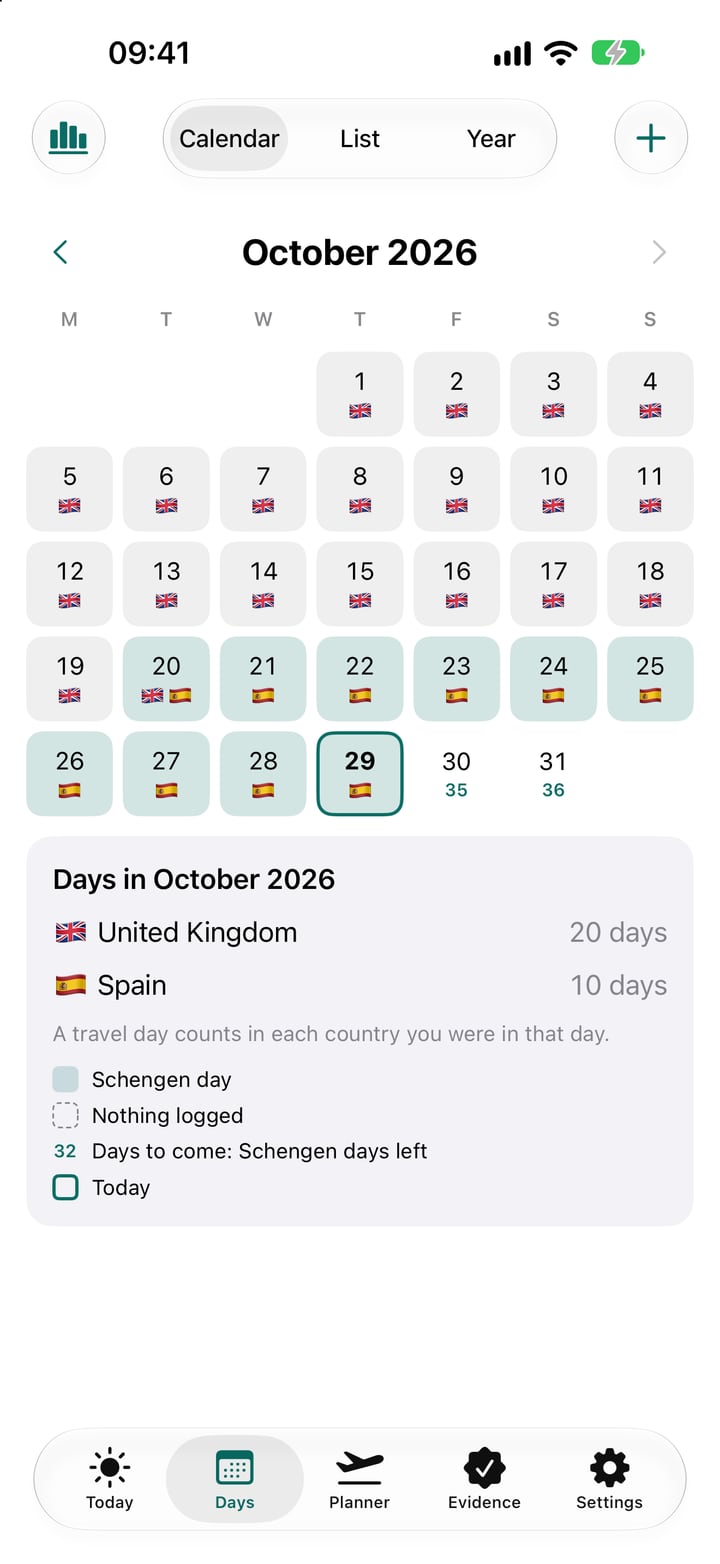
Your day limit is set by your ties and your departure year. That is the part we plan with you.
HMRC’s guidance (RDR3) expects you to keep records of where you were and when. Once your limit is set, RezTally keeps the count and that kind of dated record.
RezTally is our own iPhone app that keeps a record of which country you are in each day. See reztally.com for where it stands.
Telling HMRC
The P85 is paperwork. The test decides.
What you send depends on how you were taxed before you left.
| You | HMRC needs | Watch for |
|---|---|---|
| Employed, on PAYE only | A P85, with the leaving details from your P45. | It closes your PAYE record and claims back overpaid tax. Nothing more. |
| Already in Self Assessment | A return for the year you leave, with the residence pages (SA109). | The split-year claim is made here. No separate P85. |
| Keeping UK rent or other UK income | A return for every year you have it. | Tax taken off the rent by an agent does not replace the return. |
| No UK income left | A request to come off Self Assessment. | Stop filing without telling HMRC and unfiled returns pile up. |
The five-year shadow
Come back within five years and the tax comes back too
The temporary non-residence rule
Before you go
Four in seven
UK resident in at least four of the seven tax years before you left.
While you are away
A sale or payout
A gain, a dividend from your own company, a pension drawdown.
Back within five years
Taxed on return
As if it arose in the tax year you come back.
Away for longer
Outside the rule
Five years exactly is not enough.
In its reach
- Gains on assets you owned before you left.
- Dividends from your own closely held company.
- Pension drawdown and some lump sums.
Outside it
- What you earn from your work in Dubai.
- Most assets bought and sold while you are away.
- Visits to the UK, while you stay non-resident.
Since 6 April 2026 the whole dividend is caught, including profits your company made while you were away.
What goes wrong
Four ways a clean exit comes undone
Common patterns, not client stories. None looks like a mistake at the time.
Assumed
“We kept the house, just in case.”
What the rules see
A home available to you is a tie. Time spent in it can undo the split year.
Assumed
“The family will follow after the school year.”
What the rules see
A spouse or child in the UK is a tie from day one. Your day limit drops.
Assumed
“I sent the P85, so HMRC knows.”
What the rules see
If a return was due, the split-year claim was never made.
Assumed
“I sold the business from Dubai, then came home in year four.”
What the rules see
The gain is taxed in the year of return, as if you had never gone.
Where the UAE side meets it
Two calendars, one plan
The company, the visa and the home in the UAE each set a date the UK side depends on.
The first step
Start with the free tools. Bring the result to the call.
A tool gives a first indication from the answers you type. It cannot test them.
Have these to hand for the review
- The date you plan to leave, or left.
- What happens to your UK home.
- Where your family will be, and when.
- The UK days you expect each year, work days included.
- Anything you may sell or draw in the next five years.
Sources
Where each fact comes from
As at November 2026. Rules change. Check the source or ask us before you act.
UK tax in this guide is general information. Advice on your facts comes from a UK-registered tax adviser we work with.
Who you deal with
Alan Underwood

Founder of Dubai Transition Consultants. He moved himself and his businesses from the UK to the UAE, and he is the person you speak to.
We plan the departure year with a UK-registered tax adviser, and set up the company, visas and bank account to the same dates.
“It’s great to talk to a human.”
Said to Alan on a first call.
Version 1.0 · November 2026 · Written by Alan Underwood
General guidance, not personal legal, tax or financial advice. UK and UAE rules change and individual circumstances differ. Speak to us, or another suitably qualified professional, before acting. Personal UK tax advice comes from a UK-registered tax adviser. Dubai Transition Consultants is a trading name of Dynamic Transition Consultants FZCO, Dubai Silicon Oasis, Dubai, United Arab Emirates.